Multigenerational HOMES Act
Creates a tax credit for qualifying home changes that support older or disabled relatives or provide housing for family caregivers.
In the House Ways and Means Committee since Oct. 1, 2026, 7 days after it was introduced. Most bills never leave committee.
- INTRODUCEDINTROOCT 1, 2026
- COMMITTEECOMM.IN COMMITTEE
- HOUSEHOUSE—
- SENATESENATE—
- LAWLAW—
What the bill would do, and why it matters
Families sometimes adapt homes so older or disabled relatives can live with them, or so relatives can provide care. The bill would create a tax credit for certain costs of those changes. It would limit the credit by income and by a lifetime cap for each home, while allowing some lower-income taxpayers to receive a refundable credit.
- INTRODUCED ONLY This bill has been introduced and possibly referred to a committee, but it has not passed any vote. Most introduced bills never become law — they die in committee without a hearing.
- DATA NOTE No Congressional Research Service summary was available.
- Creates a renovation tax credit
Eligible taxpayers could claim a credit equal to 15% of qualifying renovation expenses, up to a lifetime total of $7,500 for each qualified dwelling unit. The limit is shared with a spouse’s prior credits for that home.
- Defines qualifying homes and renovations
The credit would cover certain property, installation labor, and inspections for changes that improve safety, mobility, or accessibility for a qualifying relative, or provide living quarters for a qualifying relative who cares for the taxpayer. The home must be the taxpayer’s main home or a secondary unit on the same property, and the relative generally must be at least 65 or disabled and live there for more than half the tax year.
- Adjusts the credit for income
The credit would begin to phase down when modified adjusted gross income exceeds $200,000, or $400,000 for a joint return, with the reduction calculated over $75,000 of excess income. For taxpayers whose adjusted gross income is no more than the area median income, the credit would be refundable.
- Allows unused credits to carry forward
If a taxpayer cannot use the full credit because of the tax-limit rules, the unused amount could carry forward for up to five succeeding tax years. Taxpayers would have to provide documentation to substantiate the expenses.
The bill would use the tax system to offset part of the cost of adapting a home for multigenerational living or family caregiving. The practical effect would depend on whether a household’s renovation, home, family relationship, and income meet the bill’s rules.
Written from the bill text.
The path it took, step by step
- IntroducedOCT 1, 2026HOUSEOCT 1, 2026By Rep. Strickland with 1 original cosponsorReferred to Ways and Means
- SAME DAYNOWHouse committeeOCT 1, 2026WAYS & MEANS NOWOCT 1, 2026In committee for 7 daysNo hearing yet
- 7 DAYS SO FARPassed the House—HOUSE FLOOR—Not scheduled
- Senate committee—SENATE—
- Passed the Senate—SENATE FLOOR—Not scheduled
- Resolve differencesONLY IF NEEDEDBOTH CHAMBERSONLY IF NEEDEDSkipped if the other chamber passes the same text
- Signed into law—PRESIDENT—10 days to sign or veto
- OCT 12026OCT 1, 2026REFERREDHOUSEReferred to the House Committee on Ways and Means.
- OCT 12026OCT 1, 2026INTRODUCEDHOUSEIntroduced in House
At day 7, this bill is already older than 3% of the laws passed this Congress were when they were signed.
Where your members stand on it
Support from one state
Plus the sponsor, a Democrat. Every cosponsor is from one party.
Plus the sponsor, a Democrat. Every cosponsor is from one party.
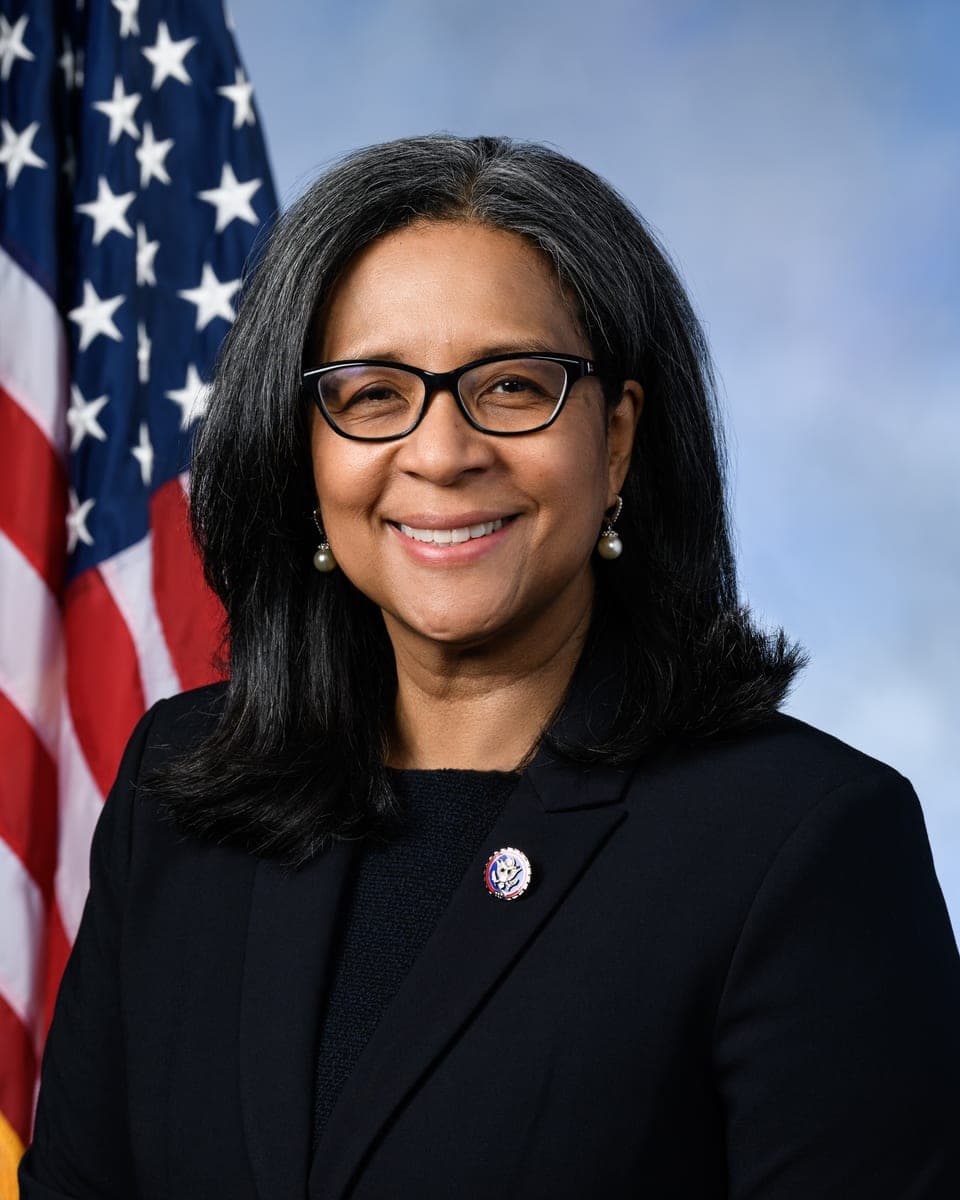
Rep. Strickland’s record: sponsored 30 bills this Congress. 1 passed the House; 1 became law.
- David P. JoyceR-OH-14ORIGINAL
What readers think
Discussion
Get an alert when it changes stage, gets a floor vote in the House, or is signed into law.